
Major Shareholders Benefit From Delisting Rules
The Hidden Risks of Delisting Policies
A growing concern in the financial sector is the unintended consequences of delisting policies that disproportionately benefit major shareholders while harming individual investors. This phenomenon has raised questions about whether these policies are truly designed for the public good or if they have become tools for private gain.
The Korea Exchange introduced a policy this year to delist companies whose market capitalization falls below certain thresholds. For KOSPI, the threshold was increased from 20 billion Korean won to 30 billion won, and for KOSDAQ, it went from 15 billion won to 20 billion won. Approximately 100 stocks are now at risk of delisting under this policy.
At first glance, the policy seems beneficial as it aims to remove underperforming companies from the market, thereby improving the overall health of the stock market. However, industry insiders warn that there are systemic flaws in this approach.

Owner Families’ Stake Surges by 10 Percentage Points After Liquidation Trading
One example of how delisting can strengthen major shareholders’ control is seen in the case of Iljeong Industrial, a former KOSPI-listed company. Despite its long history, the company fell below the market capitalization threshold and began the delisting process.
During liquidation trading, the owner family significantly increased their stake. According to the Financial Supervisory Service’s DART system, the combined stake of the largest shareholder and related parties rose from 65.2% to 75.44%, a 10.24 percentage point increase. This aggressive acquisition of shares during a time of panic among small shareholders highlights the potential for exploitation.
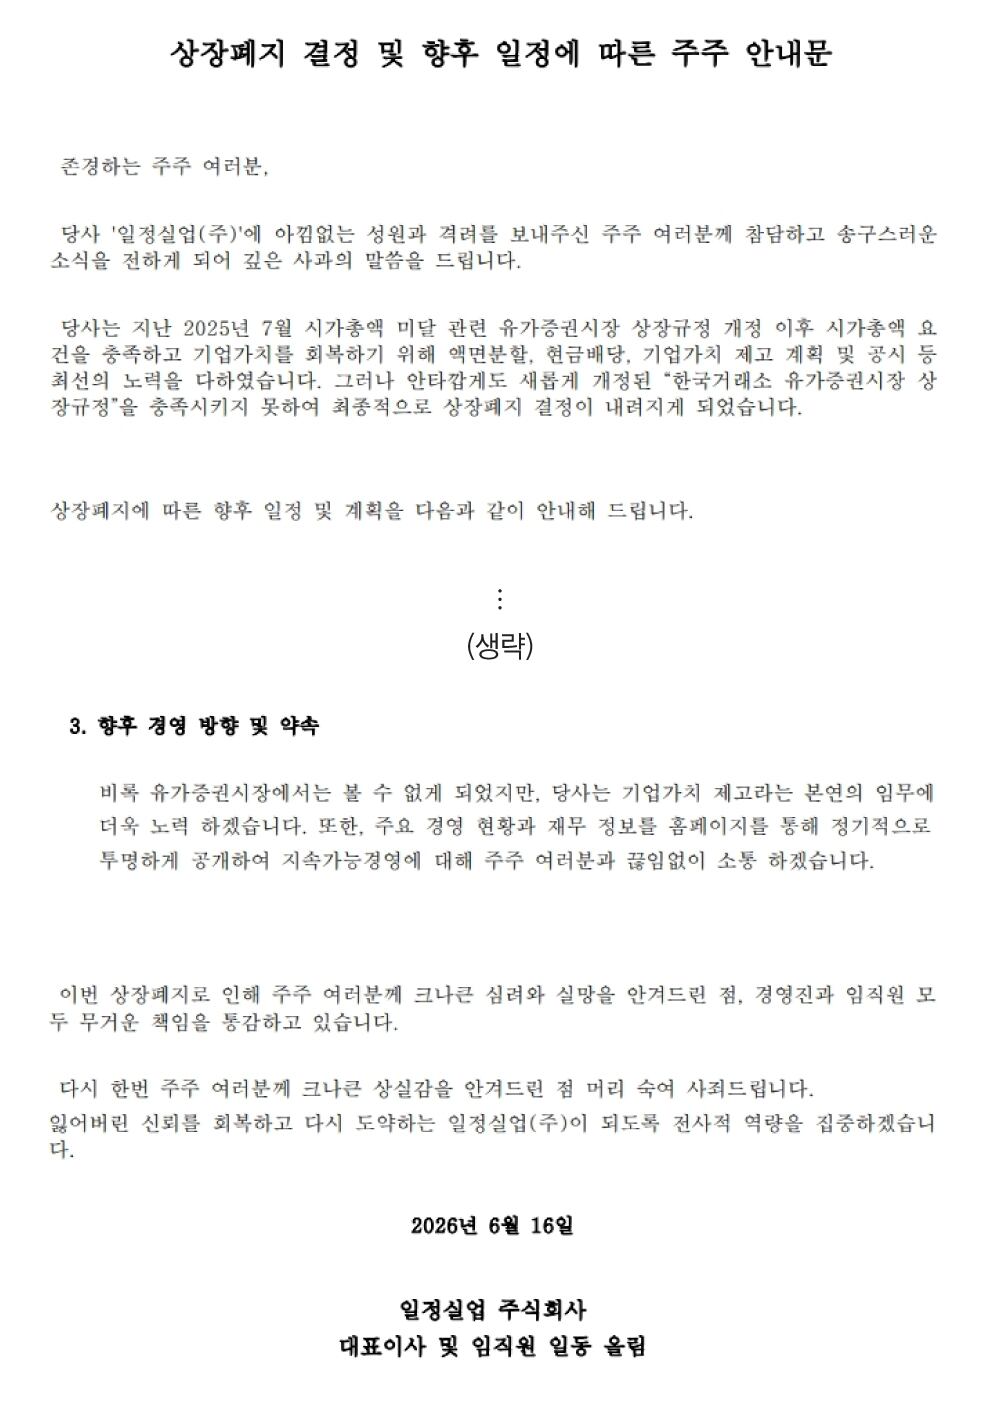
“Thank You, Liquidation Trading”—Delisting Can Be Beneficial?
A critical flaw in the current system is that major shareholders can acquire shares at bargain prices during liquidation trading. This creates an opportunity for them to reduce tax burdens during inheritance or gifting. Additionally, since delisting due to insufficient market capitalization is a “forced exit,” major shareholders are not obligated to buy out small shareholders.
In contrast, voluntary delisting requires a public tender offer to purchase all small shareholders’ stakes at a price higher than market value. This discrepancy allows major shareholders to strengthen their control at a “bargain price” while small shareholders lose liquidity and are forced to sell at fire-sale prices.
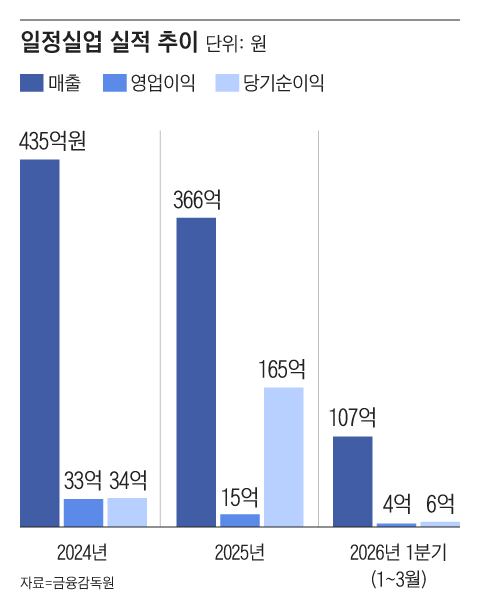
Delisting Poses No Real Threat to Owner Families
Delisting does not necessarily mean corporate liquidation. Major shareholders retain control and face almost no real impact. However, small shareholders suffer significant losses. For individual investors, liquidity is crucial, but once stocks become non-listed, trading channels are blocked, effectively freezing their funds.
Industry sources suggest that applying a “minimum price standard” reflecting book value per share (BPS) when major shareholders purchase shares during delisting could help protect small investors. Full-time investor Kim emphasized that while major shareholders can scoop up shares at fire-sale prices, individual investors have no choice but to panic-sell.
If a company’s net assets far exceed its market cap, there should be a price floor for major shareholders to follow during liquidation trading. This would ensure that the policy’s intent of exiting insolvent companies is not undermined by the exploitation of small shareholders.
The Need for Safeguards
While the policy’s rationale of removing insolvent companies is understandable, the lack of safeguards for small shareholders raises serious concerns. Industry insiders argue that supplementing the policy with measures to protect individual investors is urgent.
The current system allows major shareholders to exploit the delisting process, which could lead to a distorted market where only a few benefit at the expense of many. As more companies face delisting risks, the potential for repeated exploitation increases, making it imperative to address these systemic issues.
Post a Comment for "Major Shareholders Benefit From Delisting Rules"